The workers who lost their job and their savings on the same day
Thousands of Enron employees held their retirement savings in Enron shares. When the company failed, both halves of their life went at once. The lesson is not about fraud.
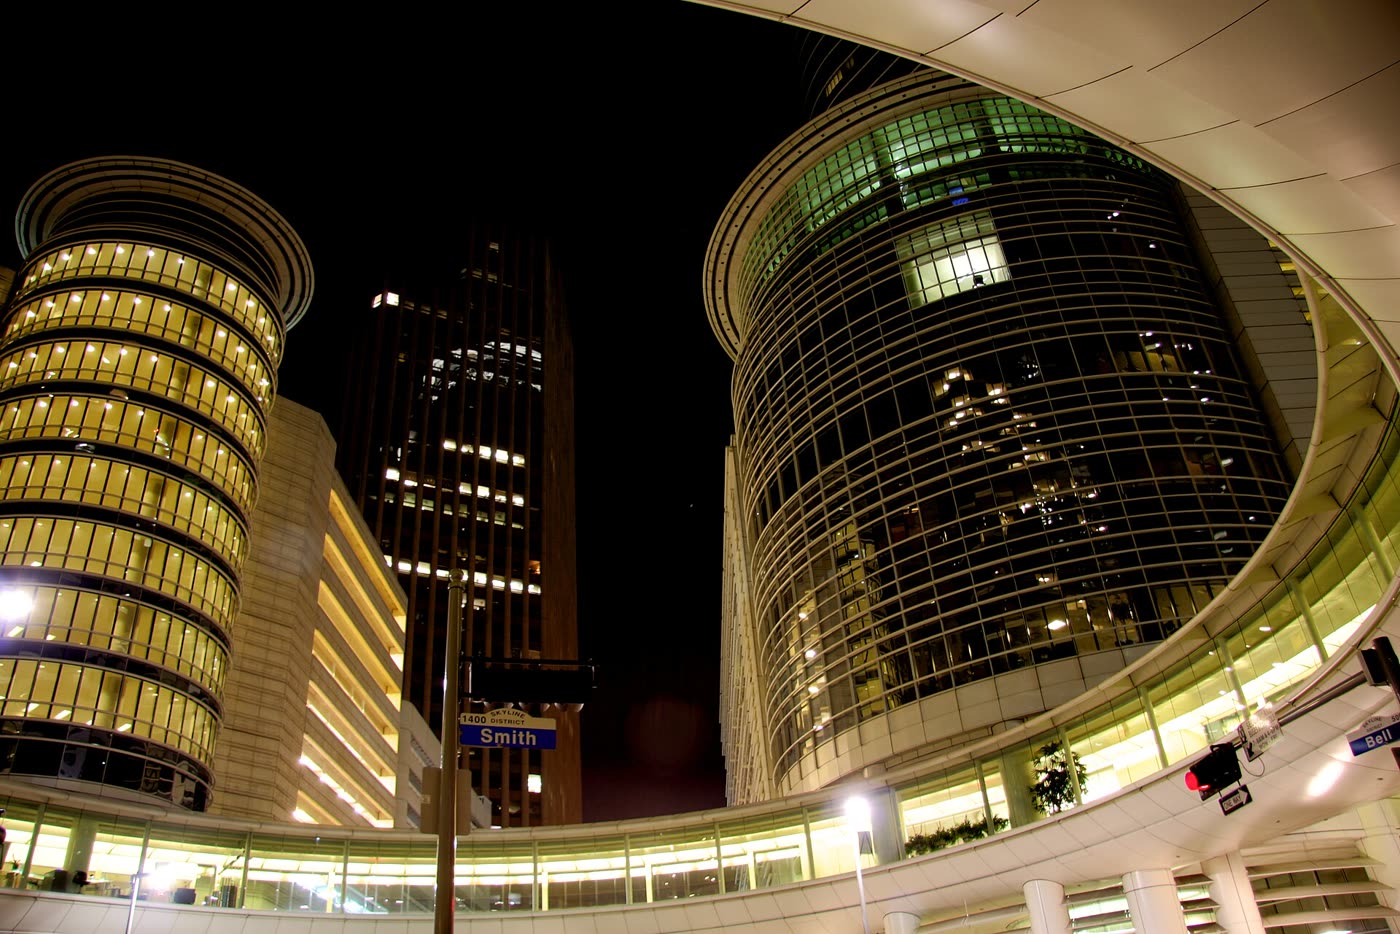
In December 2001, employees at Enron's headquarters in Houston were told to collect their belongings and leave. Many carried out cardboard boxes in front of television cameras, and the footage became the image of the scandal. What the cameras could not show was the second loss happening quietly at the same moment. A very large number of those people had spent years putting their retirement savings into shares in the company that had just fired them. They lost the job and the savings in the same week, for the same reason.
How it happened without anybody being reckless
It is tempting to assume these were gamblers. They were not. They were doing something that felt sensible and was actively encouraged.
Enron, like many large American employers, ran a retirement plan in which staff could invest their own contributions, and the company matched part of what they put in. That match was paid in Enron shares. On top of that, many employees chose to put their own contributions into Enron shares too, because the company had been one of the great success stories of the 1990s and buying into it looked like confidence rather than risk.
So a very large share of the retirement plan's total assets sat in a single stock. Not a sector, not an index. One company, and the same company that paid their wages.
The concentration nobody names
Every investor is told to diversify, and most people think they understand it. Do not put everything in one place. The Enron employees would have agreed with that sentence and would still have done exactly what they did, because the danger was not obvious from where they stood.
Owning shares in your employer is not one bet. It is the same bet twice. Your salary, your job security, your health cover, your references and your savings all depend on the same company continuing to do well. When it does, everything is wonderful at once. When it does not, everything fails at once, and it fails precisely when you most need something to fall back on.
That is the part worth carrying away. The risk was not that Enron shares might fall. It was that they would fall on the exact day the salary stopped.
And then the doors were locked
There is a detail that turns the story from unfortunate into cruel. During the autumn, as the share price was collapsing and it was becoming clear how much trouble the company was in, the retirement plan was going through an administrative change of provider.
During that changeover there was a blackout period in which employees could not move their money. People watched the value of their savings fall day after day and were unable to sell. By the time the plan reopened, the damage was done.
Some of them were within a few years of retiring. A working life of saving, and the thing they had saved into was worth almost nothing.
The lesson is not about fraud
Enron is usually told as a story about accounting, and the accounting was genuinely fraudulent. Executives went to prison. The auditor collapsed with the company. All of that is true and all of it is well covered elsewhere.
But treating it purely as a fraud story lets everyone off too easily, because it suggests the only way to lose like this is to be lied to. The concentration was visible to anybody who looked. It was not hidden in a footnote. Thousands of people were holding a single stock that was also their entire livelihood, and almost nobody named it as a risk while the price was rising.
Company shares are still a normal part of pay, particularly in technology. If you are ever offered them, they can be a genuinely good thing to hold. The question worth asking is not whether the company is any good. It is what happens to the rest of your life on the day those shares fall by ninety per cent, and whether you would still be standing.
What to do if you are ever offered it
This is not an argument for refusing company shares. They are often a genuine part of pay, sometimes at a discount, and turning them down means turning down money.
The useful habit is to separate two decisions that usually get made as one. The first is whether to accept the shares, and the answer is normally yes. The second is whether to keep holding them years later, and that is a different question with a different answer.
Most people never make the second decision at all. The shares arrive, they sit there, and holding becomes the default simply because selling requires an action and loyalty makes it feel disloyal. Meanwhile the position quietly grows into the largest thing anybody owns, attached to the same employer that pays the rent.
A reasonable rule is to decide in advance what share of your savings you are willing to have in your employer, and to sell down to it on a schedule rather than in a panic. The number matters less than having one, because the danger is not picking the wrong limit. It is never noticing that you had no limit at all.
The takeaway
Diversifying is usually explained as a way to smooth out returns, which makes it sound like a preference. Enron shows what it actually is. It is the difference between one bad thing happening and every bad thing happening at once.
This article is educational and reflects the views of the Wealth Stratum community. It explains a general investing concept in plain terms and is not financial advice or a recommendation to buy or sell any security. Always do your own research. Photograph of the former Enron complex by Alex, used under the Creative Commons Attribution 2.0 licence.